
The Democratic wave was expected, but not its scale. A veritable tidal wave has swept across the US electoral map, sweeping away everything in its path, including historically Republican states such as Texas, South Carolina and Kansas (a first since… 1932). Although not all results are in yet, there is already no doubt that Donald Trump has lost control of the House of Representatives and, above all, the Senate, where the Democrats have so far managed to win back six seats and are therefore expected to hold, at the very least, a majority of 54 seats. This marked the most stinging defeat for a sitting president since 1946, yet it was not entirely unexpected, given that Trump’s unpopularity had reached historic levels against a backdrop of distrust of his immigration policy, his attacks on institutions and, above all, his confrontation with Iran. Elected to tackle the high cost of living, the US president has, paradoxically, pursued policies that have contributed to rising inflation – first by launching a trade war and then by embarking on a risky military campaign in Iran. This weakness was exploited to the full by the Democrats, who centred their election message on Americans’ purchasing power – a strategy that has now enabled them to take control of Congress in Washington.
However, this victory does not mean that the party will be able to implement its programme. Indeed, the President of the United States retains the veto power, which is likely to block any legislation with which he disagrees. It is true that in recent hours Trump has signalled a willingness to cooperate with the Democrats, but the political reality and the pressure his party is bound to exert should dissuade him from conceding any significant victories to his political opponents in the run-up to the 2028 presidential election. Furthermore, the Democrats’ determination to launch parliamentary committees of inquiry into allegations of personal enrichment levelled at Trump is bound to strain relations with the US President and undermine any prospect of cooperation between the legislative and executive branches. The current situation therefore risks leading to an institutional deadlock with no significant progress on fiscal policy, which should limit the widening of the budget deficit and thus mitigate one of the factors exerting upward pressure on US government bond yields. The risk with this base-case scenario is that the final result could be even more favourable to the Democrats, who, according to some projections, could win up to 57 seats in the Senate; in that case, around ten defections from the Republicans would be enough to secure the two-thirds majority needed to override a veto or impeach the president, although this scenario remains unlikely at this stage.
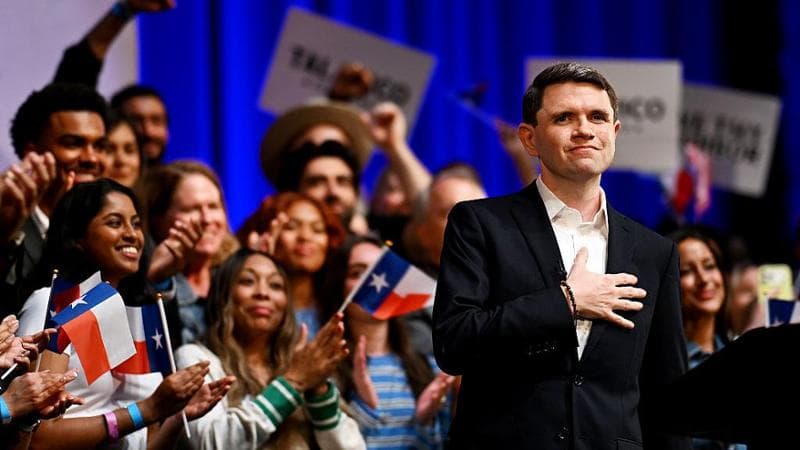
Although attention has been focused entirely on the elections for the House of Representatives and the Senate in recent weeks, the real stakes of these elections for the financial markets undoubtedly lay in the race for the position of governor of Texas. Indeed, the Republican Abbott was regarded as one of the leading advocates of data centre development, as evidenced by the fact that his state alone accounted for almost a third of the capacity currently available or under construction in the United States. Although the polls had him as the favourite until last night, he ultimately lost to Hinojosa, a Democratic candidate who made the regulation of tech giants the central theme of her election campaign. Added to this are the numerous referendums and local votes in a region accounting for 170 of the 300 GW of planned capacity in the United States, the provisional results of which are conclusive, with the adoption of around twenty restrictive measures aimed at curbing the creation of new data centres.
The initial reaction of the equity indices clearly highlighted this risk, with a significant fall in the Nasdaq (-2 per cent) and the Korean Kospi index (-4 per cent), before they gradually recouped their losses to return to equilibrium this morning. Investors are hoping that the anti-artificial intelligence rhetoric was merely an election ploy and that the Democrats will prove more pragmatic once in power. Indeed, the new governor of Texas’s programme does not envisage a total ban on the construction of data centres, but rather the introduction of regulations aimed at protecting rights and limiting additional costs for households.
Uncertainty is therefore likely to persist in the short term, whilst negotiations between the tech giants and the new local authorities could lead to potential agreements. However, as visibility improves, investors should regain their appetite for risk, allowing equity indices to resume their upward trend. In this regard, it is worth noting that the year following mid-term elections, when power is shared between the two parties, has historically been one of the best periods for equity markets. This favourable “seasonal” trend, combined with global economic growth that remains solid, exceptional corporate earnings and valuations that have returned to particularly attractive levels, leads us to maintain a positive outlook on the equity market, whilst diversifying our allocation across other sectors and geographical regions, as well as into fixed income, to capitalise on the decorrelation between the two asset classes.
*Multi-Asset & Overlay Portfolio Manager, Edmond de Rothschild AM