
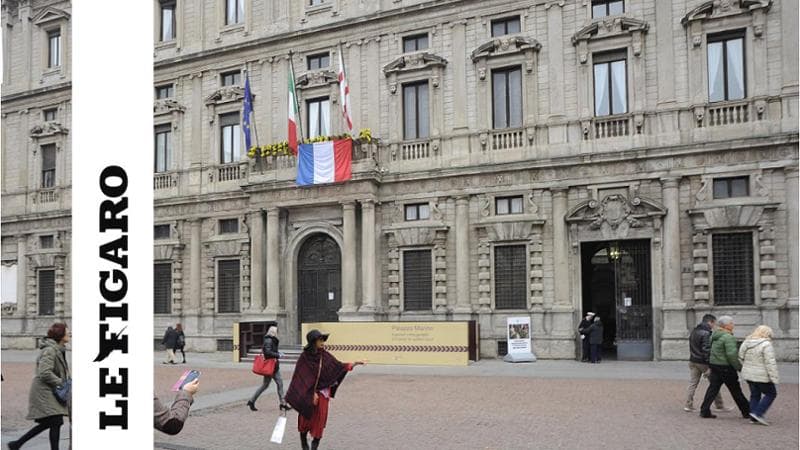
One of Milan's most exclusive addresses is Via dei Giardini 16, the former villa of Santo Versace, the billionaire fashion entrepreneur and former Italian politician. Today, it houses The Wilde, one of the most exclusive private members' clubs in Italy's financial capital.
Since opening in 2024, the club has become a meeting place for leading figures in finance, business and fashion. They gather to network amid fine woodwork, luxurious fabrics, leather and contemporary art. Over glasses of champagne, conversations flow in Italian, English and, increasingly, French. Membership is, of course, highly selective (Théodora de Soultrait, sister of entrepreneur and Vicomte A. founder Arthur de Soultrait, oversees the process), and comes with a €4,000 joining fee and an annual subscription of €1,250. But money is rarely an issue for the foreigners who choose to settle in Milan.
Quite the opposite: moving to Italy with their families can allow them to make substantial tax savings. Consider the figures. Under Italy's preferential tax regime for wealthy new residents, those who qualify can pay an annual flat-rate tax of €300,000 on their foreign-sourced income, plus €50,000 for each family member included in the scheme. The previous rate of €200,000 continues to apply to those covered by the earlier rules. The regime does not exempt beneficiaries from all Italian taxes, but it offers considerable advantages to people with substantial income from abroad.
Admittedly, you have to be extremely wealthy to benefit from such a scheme and be happy to pay "only" €300,000 in tax each year.
Yet the Italian flat-tax regime, introduced in 2017 and available for up to 15 years, has proved highly successful. It has been dubbed the "footballers' tax" ever since Cristiano Ronaldo took advantage of it when he joined Juventus in Turin in 2018. The former Real Madrid player is said to have saved several million euros thanks to the scheme.
Milan is proving particularly popular
Since the scheme was introduced, some of Europe's wealthiest individuals have set their sights on Italy, which has become a favoured destination for those looking to relocate abroad. According to a report by British consultancy Henley & Partners, Italy is among Europe's leading destinations for relocating millionaires.
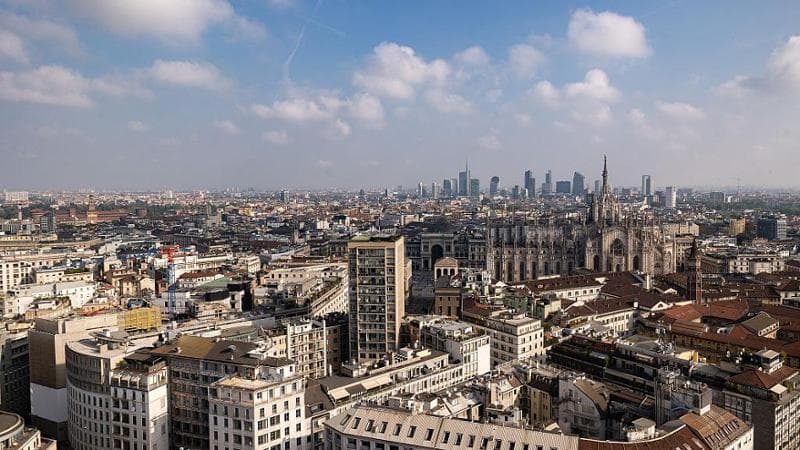
Italy was expected to attract a net inflow of 3,600 millionaires in 2025, according to Henley & Partners' estimates. Milan has proved particularly popular, establishing itself as an international financial centre and a hub for family wealth management, especially since the UK's Labour government abolished the country's "non-dom" tax status.
Under that regime, UK residents whose permanent home was considered to be elsewhere could avoid paying British tax on foreign income and gains, provided they did not bring the money into the country. It was particularly advantageous for expatriates and wealthy investors.
Since its abolition, numerous financial institutions have relocated entire departments to Milan, particularly in private equity and mergers and acquisitions, where earnings can be astronomical.
French investment firms have also seized the opportunity. Ardian, Astorg, Eiffel Investment Group and Eurazeo have all recently opened offices in Milan, attracted by the expertise of financial professionals based there, including Yoël Zaoui and François de Mitry, as well as by the dynamism of Italian capitalism.
Italy, the eurozone's third-largest economy, has regained its footing, although its public debt remains high.
Indeed, in its annual report on public finances, published on 25 June, the French Court of Auditors urged France to draw inspiration from Italy's approach to managing its public finances.
Italy's appeal extends well beyond Milan. From Rome, Florence and Venice to Sardinia, Puglia and the Amalfi Coast, French is heard more and more often. Italy has always had plenty to offer — a relaxed lifestyle, an extraordinary cultural heritage and world-renowned cuisine — but it has now added another attraction: a favourable tax regime that many French taxpayers can only dream of.
Along with Belgium and Denmark, France has one of the highest tax burdens in Europe. According to OECD figures, compulsory taxes and social contributions account for more than 45% of French GDP, among the highest levels in developed economies.
For the highest earners, the top marginal income tax rate reaches 45%. Once the CSG and CRDS social levies and other social security contributions are added, the overall tax burden can be considerably higher. Then there is the property wealth tax (IFI), inheritance and gift taxes, which are among the highest in Europe, and a flat tax of 30% on most investment income and capital gains.
"A deep sense of frustration"
Faced with this array of taxes, growing numbers of French people are considering leaving the country, particularly the wealthiest, who fear they could sooner or later find themselves in the sights of a government desperately short of money. The debate over the proposed Zucman wealth tax remains fresh in everyone's minds.
"We're hearing from a lot of French people," says Emmanuel Di Girolamo, a property adviser at the Puglia in Paris agency. "Many are worried about the prospect of the 2027 presidential election. They want to buy now, thinking that if things go well, they'll at least have acquired a lovely second home. And if things go badly — from their point of view — they'll be able to leave quickly. I hear this kind of talk almost every week. You can sense an immense frustration among our French clients."
Those considering a move abroad have often already studied the intricacies of Italy's tax system. To qualify for its benefits, however, they must become Italian tax residents. Italian tax residency is determined by statutory criteria, including physical presence, residence and personal or family ties. Simply owning property in Italy is not enough.
Alongside wealthy individuals, Italy also offers tax incentives designed to attract senior executives and other highly qualified professionals through its impatriati scheme.
Under this scheme, qualifying workers who transfer their tax residence to Italy can benefit from a 50% reduction in their taxable employment or self-employment income, up to an annual income ceiling of €600,000. The reduction can rise to 60% for those who meet certain conditions relating to minor children. The relief generally applies for five years and is subject to specific professional and residence requirements.
The previous regime, which applied to eligible workers who relocated before the introduction of the new rules in 2024, offered more generous tax relief, potentially reaching 90% in certain circumstances.
"That encouraged a lot of people," says a French entrepreneur based in Italy. "For five years, we paid practically no tax at all, which really gave us the opportunity to save money."
In 2019, apparently inspired by the success of Portugal's programme, Italy also introduced incentives to attract foreign retirees, offering eligible pensioners a flat tax rate of 7% on their foreign-sourced income, including pensions.
The preferential regime is available for a limited period and is subject to specific conditions. Applicants must transfer their tax residence to a qualifying Italian municipality, generally one with fewer than 20,000 inhabitants in designated regions of southern Italy, or to certain smaller municipalities in central Italy covered by special provisions.
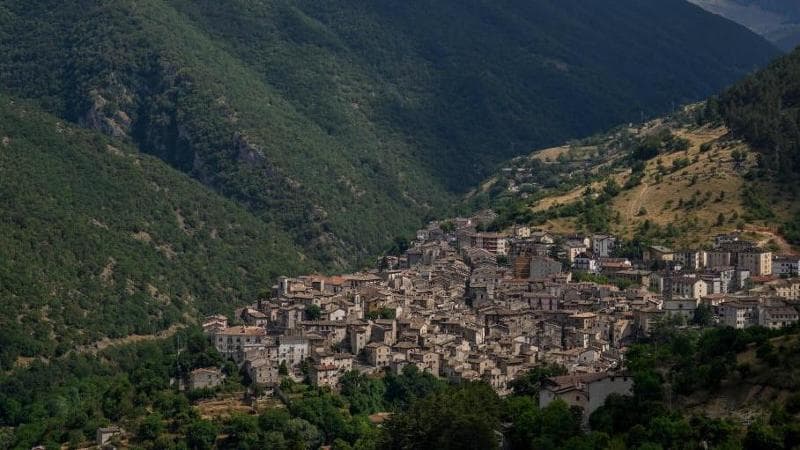
Approximately 66,000 French retirees currently live in Italy. Towns such as Presicce-Acquarica in Puglia, Santo Stefano di Sessanio in Abruzzo and Riace in Calabria are experiencing a real demographic revival, driven by new foreign residents who are renovating abandoned homes, supporting local businesses and breathing new life into villages that had been slowly dying.
Another major attraction is Italy's inheritance and gift tax system, which offers substantial advantages compared with France.
"The best way to avoid paying too much tax in France on inheritance and gifts is to move to Italy," says Swiss lawyer Philippe Kenel, a specialist in helping wealthy individuals relocate.
For direct heirs — spouses, parents and children — the Italian inheritance tax rate is 4% on the portion of an inheritance exceeding €1 million per beneficiary. This allowance was introduced in 2006 by Silvio Berlusconi's government. In other words, each child can inherit the first million euros entirely tax-free, provided the estate is subject to Italian inheritance tax and the relevant exemption is available.
Inheritance tax
Above that threshold, the rate is just 4%. For inheritances between siblings, the rate is 6%, with a €100,000 exemption. For unrelated beneficiaries, it rises to 8%, with no exemption. The comparison with France is striking. For direct descendants, French inheritance tax follows a progressive scale, with rates rising from 5% to 45% and a standard exemption of €100,000 per child.
For large estates, the difference can be substantial.
Consider an inheritance of €1.1 million left to a single child. Assuming the full Italian exemption is available, the inheritance tax would amount to just €4,000 in Italy. In France, the tax bill could be considerably higher, depending on the circumstances.
For an estate worth €5 million divided equally between two children, Italian inheritance tax would amount to approximately €120,000, assuming the standard exemptions apply. On an estate worth €10 million, again divided equally between two children, the corresponding Italian tax would be approximately €320,000.
French inheritance tax on estates of this size can be substantially higher. However, the precise difference depends on several factors, including the beneficiaries' circumstances, previous gifts and the applicable exemptions. Moving to Italy does not automatically eliminate potential French inheritance-tax liabilities.
Italy offers another significant advantage to beneficiaries of its preferential flat-tax regime for wealthy new residents: subject to the applicable conditions, inheritance and gift taxes may be limited to assets located in Italy.
For a French family whose wealth consists mainly of securities, company shares or property held outside Italy, this provision can offer considerable tax advantages. The outcome, however, depends on the family's circumstances and on the interaction between Italian and French tax law.
The translation of this article was reviewed by a Language Service Provider